Showing posts with label Car Insurance. Show all posts

Thursday, 15 September 2016

Topmost Car Insurance Myths – Busted

Topmost Myths People Consider about Car Insurance and Misconceptions Busted - Insurance Classified

Do you know everything about the car insurance your broker or insurance company is offering you? You probably don’t!

Like in driving, where most of us are in misconceptions such as “I am perfect in driving and accident will never happen to me” or “that animal (dog or cow) will not jump in front of my vehicle” abound, the car insurance also has many myths.

This topic enlightens to the people looking for car insurance and having many myths. Read below these myths and misconceptions busted:

  • Myth: Buying Car Insurance is a clumsy and complex process
Reality: Buying best policy plan or renewing car insurance has never been easier.

Myth: Buying Car Insurance is a clumsy and complex process

The process has become easy with internet technology. Through filling some basic information, customer will get an instant quote of premium plan and can get policy at their place by following few steps.

In case of policy renewal, some insurance companies follow advance technology such as Photo Quote option, wherein customers only need to upload photo of the existing policy. After that, they will receive a quick quote to renew their policy.

  • Myth: If I will change my insurance company to another, I will fail to get my NCB (No Claim Bonus)
Reality: Customer will get their NCB bonus whether they change their insurer


Myth: If I will change my insurance company to another, I will fail to get my NCB (No Claim Bonus)

Customers will get NCB benefits if they don’t file any claim during the policy period. This benefit will be added as a discount to the premium for next year renewal. And, yes definitely NCB is transferable to other insurer. Customers should make sure the transferable period while purchasing the policy. Some insurers provide this till the expiry date and some other consider within 90 days of expiry.

  • Myth: Car Insurance Policy gives protection against accidents only
Reality: Insurance is not only covers accidents. It also covers against man-made and natural disasters.


Myth: Car Insurance Policy gives protection against accidents only

Car insurance also provides protection against the losses/damages incurred by the natural disasters such as earthquake, flood, storm, hurricanes, landslide etc. and man-made disasters such as terrorist activity, theft, riots etc.

  • Myth: If an accident incurred, the only way is to pay from pocket first and then follow many difficult claim process
Reality: Either the customers need not to pay or if pay, they will get reimbursed afterwards.


Myth: If an accident incurred, the only way is to pay from pocket first and then follow many difficult claim process

Customers can find a list of networked garages in their area online i.e. the one associated with the insurers in their list. In this case, insurer will directly settle the expanse with the garage without any issue.

In case, if the customers are unable to visit a networked garage for some reason, they can claim reimbursement and insurer will pay them directly.

  • Myth: If my car has been damaged /lost, I can claim a total sum that will be equivalent to the price of a new one.
Reality: This is not the true logic.
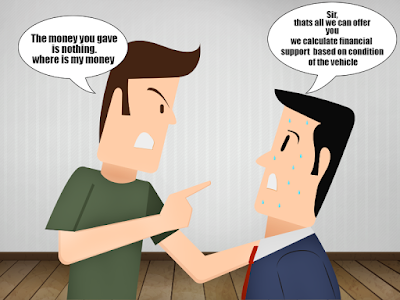
Myth: If my car has been damaged /lost, I can claim a total sum that will be equivalent to the price of a new one.

The real fact is that if a customer files a claim, he/she will get the financial support of the condition of the vehicle, which was in before the damage occurred. The true value is calculated on the basis of the current value and depreciation rate of the car.

Also Read


Tuesday, 9 August 2016

How Does Car Insurance Keep Safe During Heavy Rain or Flood?

If a person, living in a city where heavy rain or flood causes major loss, or there is always a chance of flood. People and their vehicle majorly suffer from this. Flood can damage a car, its engine or electrical system. These losses make car-insurance a must-have factor for everyone.

Get Coverage from Car Insurance

Comprehensive insurance policy covers harms or damages caused due to natural disasters such as cyclones, frost, floods, earthquake, tempest, storm, whirlwind etc.

Majorly engine and accessories damages happened by flood. A car’s engine may have damaged partially or completely. Replacing damaged engine costs a big expense. Covering this loss through Car Insurance is one of the best solutions. One should make sure the damage coverage due to flood is included in the plan as most of the insurers do not provide this coverage.


Add-ons to the car insurance policy

 Investing a small amount with more coverage option is more fruitful. Let’s have a look below the benefits of add-ons in car insurance:

 1)  Quick Roadside Assistance

Sometimes, driving a car in a flood affected area and getting stuck due to engine damage or other problems create aching experience. Roadside assistance services give comfort zone of repairing on-road damages, lugging the car to the nearest garage etc.

2)  Zero Depreciation

Opting for this ad-on, gives complete coverage of any type of damage occurred without considering depreciation as a factor.

3)  Engine Guard and Electronic Circuit Coverage

While parking car in water-affected area, may cause engine or circuit damage. This add-on can protect from such situation.

Safety Tips to Follow

Some safety tips, which every car owner keeps in mind while driving:

1)  If trapped in water, do not start car’s engine even after the water removes. In such case, disconnect the battery and tow the car to a nearest workshop.

2) If water comes into inner part, do not switch on the start. It may cause short circuit in the electronic circuit and may cause major loss to the person and vehicle.

3)  Check car brakes after exiting the water-logged area.

4)  Keep tools such as hammer in order to break window glasses of the car, if door locks gets blocked due to water.

Also read

IRDA - You and Your Motor Insurance Policy: FAQs

Saturday, 30 July 2016

Zero Depreciation Add on for Car Insurance– Best Way to Gain Complete Benefit

Depreciation is the decrement in the value of asset after its usability. Now-a-days Zero Depreciation or Nil-Depreciation has become popular with increasing awareness among vehicle in India.

In Zero Depreciation (or Zero Depth) policy, the total amount is returned by the car insurer without considering any depreciation on the value of the vehicle. This policy offers full claim without any deduction for depreciation on the value of parts replaced.

In order to opt this policy, customers have to pay little bit more in terms of premium. However, zero depreciation policy is decidedly recommended because it removes the possibility of any out-of-the-pocket expense of the vehicle owner. This best feature of car insurance policy extends to the repairing costs of plastic, fibre, glass, and rubber parts.
Zero Depreciation Add on for Car Insurance– Best Way to Gain Complete Benefit


There is a difference between standard and zero depreciation car policy. Standard policy provides depreciation rate of 0%-40% depending on the time of vehicle and type of material, customers have to spend some money from their pocket. While Zero depreciation policy, customers need not to spend any extra money from their pocket. In this case no depreciation is taken, thus leading 100% reimbursement on changing or depreciating parts.

In market, insurers such as ICICI Lombard General, TATA AIG General, HDFC ERGO General, Bharti AXA General are Reliance General are offering zero depreciation insurance policy. Customers can check them online also.

Usually, this coverage is offered on new car only and mostly it does not give coverage on vehicle more than three years old. Under this policy, Customers can only make a certain number of claims.

What is not covered in Zero Depreciation Insurance Policy?

Following are some terms, which are not covered under this policy:

1)    Wear and Tear
2)    Damage by mechanical breakdown
3)    Damage due to uninsured liability
4)    Damage due to uninsured items such as accessories, gas kit, tyres, bi-fuel

The tenure of this policy is for one year. After one year completion, policy has to be renewed. Customers can by Zero depreciation coverage online while purchasing car policy.

Also read

All You Need to Know about Motor Insurance?


Wednesday, 27 July 2016

Guideline That Can Help You Save Money on Car and Two Wheeler Insurance

To get Motor Insurance for safety of own vehicle from a trusted insurer is definitely a complex task, but if taken carefully, it will give other additional benefits. Policy buyer should approach a duly licensed agent/broker/An Insurance company registered with IRDA for buying Insurance Policy or for any other essential information. Here are some tips that you must follow while buying Car or Two Wheeler Insurance:

Guideline That Can Help You Save Money on Car and Two Wheeler Insurance

1)  Compare Policy among Top Insurers

Now-a-days, there are various website available, which enables comparison among Top Insurers to get competitive quote and buying insurance easily and hassle free. Customers should get to know top brand insurers such as Apollo Munich, Bajaj Allianz, Chola MS, Future Generali, L & T insurance, Liberty Videocon, Oriental Insurance, New India Assurance, Religare, Universal Sompo, Reliance, Bharti AXA, HDFC ERGO, IFFCO-TOKIO, MAX, STAR, TATA AIG Insurance etc. Insurance policies from these insurers are trusted and satisfactory.

2)  Read the fine prints


Policy plan on a particular website may seem to be a great deal with different discounts, but you have to be careful. Read the fine prints and understand the hidden policies to avoid hassles in the future. Many insurance service providers offer 24X7 swift, detailed and transparent assistance. Customers can get full assistance from these insurance service providers and get their best-suit insurance policy.

3)  Analyse Your Vehicle’s Price

If you want to renew your Auto Insurance, a little bit mathematics calculation can save from buying insurance at large premium. This is important to analyse your car’s market value before buying or renew your car insurance. Consider if the market value of your vehicle was Rs. 6 lakhs and after three years it is of Rs. 3 lakhs. It means your car values has depreciated by 50%. So while renewing insurance, take policy on the depreciated value i.e. Rs. 3 lakhs instead of Rs. 6 lakhs.

4)  No Claim Bonus

This bonus is rewarded by Insurer for not making any claims under current policy. After the policy matures, the premium amount can reduce by up to 50% over the years. You should be aware of this No Claim Bonus to get this benefit.

Click here to know more IRDA guideline about Motor Insurance

Tuesday, 26 July 2016

All You Need to Know about Motor Insurance?

All You Need to Know about Motor Insurance?

To own a Car for better convenience is one of the big investments of everyone’s life and definitely it costs huge amount of bucks. While owning a Two Wheeler is the first choice of most of the Indians. Its easy-to-drive and easy-to-handle features make it very popular among the teenagers as well. So, the security of the Vehicle is a must-have responsibility and a major concern for every vehicle holder.

According to the Motor Vehicle Act, 1988 “Driving a motor vehicle without insurance in a public place is a punishable offence.”

So the question comes “how to secure own vehicle from any damage or loss?” The answer is Motor Insurance.

What Motor Insurance is:

The term “Motor Insurance” gives protection to the vehicle holder to cover against:
1)    Losses or damages to the owner’s vehicle due to any unfortunate and unforeseen event and
2)    Pays for any TPL (Third Party Liability) considered as per law against the owner of the vehicle.

Types of Motor Insurance:

1)    Comprehensive Policy Plan:
       This policy covers against Third Party Liability, losses, damages to the vehicle and its owner.
2)    Liability only policy Plan:
       This policy covers only against damages occurred from Third Party action.

What Motor Insurance covers:

Comprehensive Motor Insurance policy covers following:

1)    Earthquake
2)    Land/Rock slide
3)    Terrorism Acts
4)    Fire, Detonation, Striking, Self-Ignition
5)    Theft
6)    Malicious Act
7)    Burglary/Housebreaking
8)    Flood, frost, cyclone, hailstorm, tempest, storm, whirlwind
9)    Riot, strike
10)  Accidental external means
11)  While in Transit by Rail/Road, Inland Waterways, Lift, Elevator or Air

On what basis Motor Insurance is calculated?

1)    For Own Damage:

Coverage on Motor Insurance Policy for own damage is calculated on the basis of the concept known as Insured’s Declared Value. The value, which is decided on the basis of the Manufacturer’s present value and depreciation rate based on the age of the vehicle.

2)    For Third Party Damage:

Coverage on Motor Insurance Policy for third-party damage is calculated as per the Motor Vehicle Act 1988. In this cover, Compulsory Personal Accident cover for owner-driver is also included. This coverage policy can also be extended to cover other risks such as Personal Accident to occupants of vehicle, Workmen’s Compensation to Driver etc.

What Motor Insurance excludes:

Following are the terms excluded under the Motor Insurance Policy:

1)    The policy is not considered for those, who are Not Having a Valid Driving License
2)    Breakdowns due to Electrical or Mechanical happening activity
3)    Accident has been done beyond the Geographical limits
4)    Under Drugs/ Alcoholic liquor Influence
5)    Vehicle is used for any illegal purpose

To know more about IRDAI Guideline for Motor Insurance, visit IRDAI website